Boots is set to return to Canadian family ownership after Wittington Investments, the Weston family holding company, and insurer-investor Fairfax agreed an acquisition valuing the business at about $8.9 billion, including assumed debt. At Wednesday’s exchange rate, reports put that at roughly £6.7 billion.
The deal covers Boots retail operations in the UK and Ireland, Boots Opticians, the No7 Beauty Company, and operations in Thailand and franchised markets. It is expected to complete in the first quarter of 2027, subject to customary closing conditions. Fairfax says it will provide up to $2.3 billion and expects to own 50% of the equity, while Wittington will have operational control and Galen Weston will chair Boots.
Until the transaction closes, this is an agreed takeover rather than a completed handover. There has been no announcement of mass store closures or a guaranteed expansion plan. The buyers have promised stable, long-term ownership, capital investment and renewed operating focus. Customers and 50,000 employees will reasonably want the nouns and numbers behind those phrases.
What is being bought
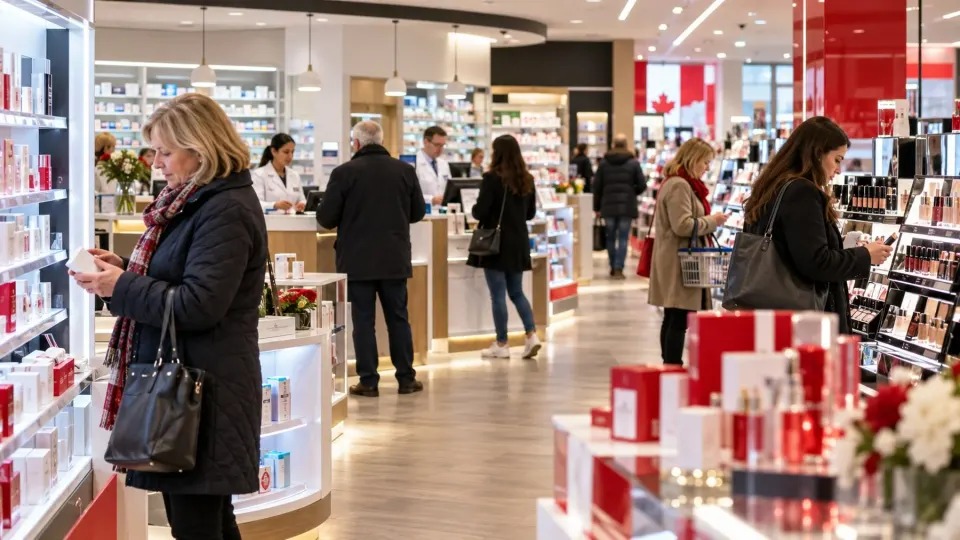
Boots is more than a beauty retailer with a pharmacy at the back. It dispenses prescriptions, provides health services, sells medicines and toiletries, operates opticians and owns the No7 brand. Reuters reported that the acquired business includes more than 1,800 stores and around 50,000 employees.
That scale explains why ownership matters. Decisions about investment, rent, staffing, digital systems and pharmacy services reach most British towns. A buyer can improve tired stores and supply chains; it can also chase margin by closing marginal branches. The announcement sets out ambition, not the eventual balance.
Wittington controls George Weston Limited, which in turn controls Loblaw, Canada’s largest grocery retailer and the owner of Shoppers Drug Mart. The family therefore understands large pharmacy, health and beauty networks. It also previously owned Selfridges before selling the department-store group in 2022. This is not a newcomer discovering that British high streets contain weather.
Fairfax brings insurance and long-term investment experience. Its promised equity leaves Wittington in operational control, an important detail because equal economic ownership does not mean equal day-to-day command.
What the price tells us—and does not
The $8.9 billion figure includes assumed debt, so it should not be read as a suitcase of cash handed directly to the seller. Enterprise-style transaction values combine equity and financial obligations. The precise financing and future balance-sheet structure will matter to how much freedom Boots has to invest.
A large price can express confidence in the brand, property footprint, customer data, own-label products and pharmacy position. It does not by itself guarantee that every branch is secure. Retail owners still examine leases, sales and local demand after a takeover.
Boots has already closed hundreds of stores in recent years as it reshaped the network. The buyers’ announcement did not provide a branch-by-branch promise. Anyone claiming either a closure bonfire or a grand reopening programme is sprinting ahead of the disclosed facts.
The deal also excludes Farmacias Benavides and Alliance Healthcare Deutschland, which remain with the current owner. That boundary matters when comparing the transaction with the wider international group previously associated with Boots.
The pharmacy question
Community pharmacy in Britain is commercially difficult and socially important. Pharmacies face staffing costs, medicine supply problems and pressure on public funding while being asked to provide more clinical services. A big retailer can spread technology and procurement costs across a network, but a national footprint also contains branches that make more sense as local infrastructure than as spreadsheet champions.
The takeover should therefore be judged partly on access: opening hours, pharmacist availability, prescription reliability and the range of services. A refreshed cosmetics aisle is welcome. It cannot conduct a blood-pressure consultation.
Consumers are also watching prices. Household budgets remain tight, as our explainer on September’s surprise fall in UK house prices showed through the wider pressure from uncertainty and borrowing costs. Boots competes with supermarkets, online pharmacies, beauty specialists and discount chains. Capital investment must improve value and service, not simply create brighter shelving for the same expensive basket.
What employees should watch
The initial announcement emphasises stewardship and investment. The practical questions are familiar: headquarters functions, store refurbishments, technology, distribution, pension arrangements and the long-term branch plan. Employees should look for commitments with dates and amounts as regulatory review and closing progress.
No responsible article can promise that 50,000 jobs are protected indefinitely. Nor is there evidence in the announcement for declaring them immediately threatened. The correct position is narrower: the workforce transfers with a major operating business, while future strategy remains to be detailed.
The owners’ Canadian pharmacy experience could support investment in digital prescriptions, loyalty, clinics and retail execution. Britain’s regulatory and NHS environment is different, so importing a Canadian playbook without adaptation would be unwise. Scale helps; local knowledge still has to answer the phone.
Why the high street still matters
Boots occupies a rare position between healthcare and shopping. A branch can draw people into a town centre for prescriptions, optician appointments and everyday purchases. When an anchor closes, the loss reaches neighbouring traders. When it is modernised, footfall can benefit the street.
Online sales will remain central, but physical pharmacies cannot be replaced entirely by delivery. Advice, urgent medicine and regulated services require people and premises. The new owners will have to make the digital and physical businesses support each other rather than stage an internal duel.
Regulators will examine the transaction and its conditions before completion. The announced first-quarter 2027 timetable is an expectation, not a certainty. Until then, the current operator remains responsible for the business.
The OutOut verdict
Boots has acquired a Canadian family, a substantial valuation and a promise of patient capital. What it has not yet acquired is a magic exemption from the economics of the British high street.
The deal could be good news if long-term ownership means repaired stores, dependable pharmacies, sharper prices and technology that helps staff. It will be less impressive if “renewed operating focus” becomes corporate dialect for discovering that several towns are inconvenient.
For now, the fairest response is cautious optimism with the receipt kept safely. The buyers have relevant experience and serious money. The next proof will not be the acquisition photograph; it will be the investment budget, the branch plan and whether customers can still find a pharmacist when the beauty counter is glowing magnificently.